

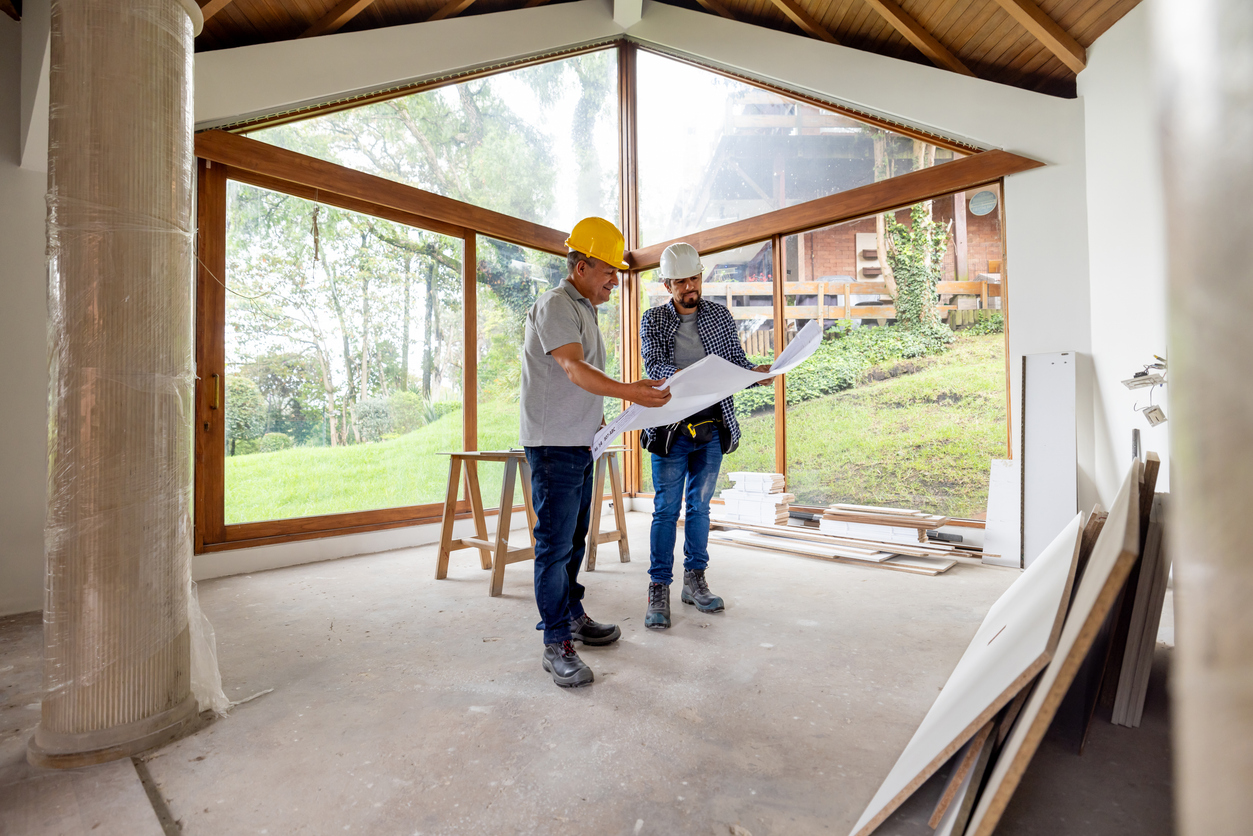
What insurance does a contractor need to work in Clifton, New Jersey? General liability and workers’ compensation are the starting point, but they don’t address every exposure. The right insurance for Clifton contractors also depends on the work involved, from remodeling older homes to demolishing and rebuilding properties or taking on larger construction projects.
Clifton’s Housing Stock and Construction Activity
According to Clifton’s 2025 Housing Element and Fair Share Plan, more than 70% of the city’s housing was built before 1960, including nearly 30% before 1940.
Vacant land is scarce, and the city reports that the majority of its recent single-family construction has involved demolishing older homes and building replacements on existing lots. Clifton also identifies 884 dwelling units for rehabilitation through 2035 under its affordable housing plan.
Renovation, demolition, and rebuilding projects each carry different risks that contractors need to consider when reviewing their insurance coverage.
Clifton Construction Insurance Basics
Under New Jersey’s home improvement contractor registration requirements, registered contractor businesses must carry at least $500,000 per occurrence in commercial general liability insurance. The state also requires workers’ compensation unless the business qualifies for an exemption.
Registered contractors must also maintain financial security, such as a compliance bond or irrevocable letter of credit, with the required amount determined by contract values. New home construction falls under separate builder registration rules, while certain state-licensed trades, including electrical contractors and plumbers, are exempt from home improvement contractor registration when working within their licensed scope.
Beyond those requirements, contractors should review coverage for their vehicles, tools, and equipment.
- Commercial auto insurance: This coverage responds to qualifying liability claims involving business-owned trucks, vans, and other vehicles. Physical damage coverage can protect the vehicles themselves.
- Tools and mobile equipment: Inland marine insurance may cover tools and equipment against specified losses, including theft and accidental damage, at jobsites or during transportation. Mechanical breakdown coverage may require separate protection.
Contractors can review New Jersey contractor insurance requirements before registering, renewing coverage, or bidding on a project.
Coverage for Renovations, Demolition, and Rebuilds
Working on older homes can expose contractors to hazardous building materials and create risks for surrounding properties. Contractors also need to account for potential damage to the structures and materials under construction.
Lead Paint and Asbestos
Renovating an older Clifton home may involve disturbing lead-based paint or asbestos-containing materials. Standard general liability policies commonly contain pollution exclusions that can restrict coverage for contamination, cleanup costs, or related injury claims.
The Environmental Protection Agency’s Renovation, Repair and Painting Rule requires covered contractors working on pre-1978 homes and child-occupied facilities to meet certification, training, and lead-safe work practice requirements, subject to certain exceptions.
Contractors pollution liability insurance may cover certain claims involving hazardous materials released during construction or demolition. However, coverage for lead, asbestos, and cleanup expenses depends on policy terms and exclusions. Contractors should confirm what their policy covers before beginning work involving potentially hazardous materials.
Damage to Neighboring Property
Demolition and excavation on closely spaced residential lots can put neighboring structures at risk. Excavating near a neighboring foundation, for example, could cause structural damage. Demolition debris could damage an adjacent roof or vehicle.
General liability insurance may respond to covered third-party property damage claims, but contractors need to check for exclusions affecting their operations.
Umbrella or excess liability insurance can provide higher limits for qualifying claims that exceed underlying policy limits. It doesn’t automatically cover losses excluded from the underlying insurance.
Builders Risk and Installation Floaters
General liability insurance isn’t intended to cover every loss to the structure a contractor is renovating or building. Property coverage needs to be addressed separately.
Builders risk insurance can protect a building and covered materials against specified losses during construction. For a renovation, contractors should confirm whether the policy covers the existing structure, the new construction, or both.
For a tear-down rebuild, coverage should reflect the demolition and construction schedule. The contractor and property owner also need to agree on who will purchase the policy and whose interests it will protect.
Installation floaters offer another option for contractors handling materials or equipment before installation. Depending on the policy, coverage may apply while materials are in transit, stored at a jobsite, or being installed.
An electrical contractor purchasing expensive equipment for a project, for example, should confirm whether those items are insured before installation rather than assuming the property owner’s insurance will cover them.
Insurance Requirements for Larger Clifton Projects
Multifamily, commercial, and mixed-use construction projects may involve insurance requirements that go beyond a contractor’s existing policies.
Owners and general contractors can specify minimum liability limits, umbrella coverage, additional insured endorsements, and other conditions in their contracts. Subcontractors should review those provisions before agreeing to the work.
Contractors may also encounter requirements for:
- Additional insured endorsements: Property owners and general contractors may require additional insured status under a contractor’s liability policy. A certificate of insurance alone doesn’t provide that status; the applicable endorsement must grant it.
- Surety bonds: Bid, performance, and payment bonds address specified bidding, contract performance, or payment obligations. They serve different purposes from New Jersey’s home improvement contractor registration security.
- Professional liability insurance: Design/build contractors and firms providing professional design services may need E&O coverage for allegations involving design errors or other professional mistakes.
A subcontractor’s current insurance limits may be sufficient for smaller residential jobs but fall short of the requirements for a larger development. Reviewing the contract before bidding helps identify whether additional coverage or endorsements are needed.
Review Your Coverage Before the Next Project
A contractor who takes on larger renovations, adds demolition services, or begins bidding on commercial work shouldn’t assume an existing insurance program covers the new operations.
Provident Protection Plus offers Clifton construction insurance options, including general liability, pollution liability, workers’ compensation, commercial auto, tools and equipment, builders risk, professional liability, and surety bonds. Depending on the business and available coverage, policies can be arranged individually or as part of a commercial package.
Before your next project or renewal, have Provident Protection Plus review your operations, insurance limits, and contractual requirements. Reach out to discuss coverage for your Clifton construction business.
About Provident Protection Plus
For more than 65 years, Provident Protection Plus has served businesses and residents across several states nationwide. Today, we are a wholly owned subsidiary of Provident Bank, the region’s premier banking institution. To learn more about our coverage options, contact our specialists today at (888) 990-0526.